Arena Signals · Public Company Intelligence · AI Infrastructure
Penguin Solutions (NASDAQ: PENG):
Building the AI Factory Platform
A memory-led earnings breakout—and a growing role designing, deploying and operating the infrastructure behind production AI.
October 7, 2026 · Incorporates results released after the close on October 6, 2026 · Fiscal Q4 ended August 28, 2026
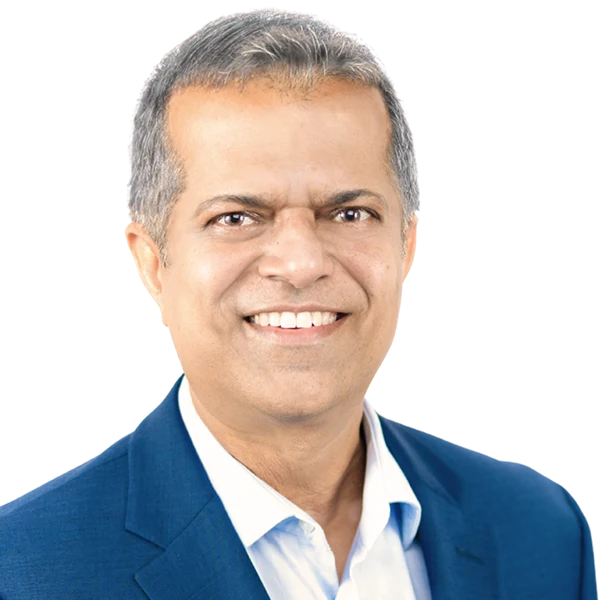
Kash Shaikh
President & CEO
“Enterprises, governments, and neocloud providers are racing to build AI factories, as platforms scale to power the next generation of inference workloads”
— Kash Shaikh · CEO · Q2 earnings announcement · April 1, 2026 · Source
01Investment Thesis — The Builder Behind Production AI
The bet is that Penguin becomes a major operating partner for the next wave of AI factories. An AI factory is a data center built to turn expensive processors, memory, networking and software into usable AI output. Penguin helps customers design the system, procure and integrate the equipment, deploy it, and keep it performing. Its proprietary cluster software and advanced memory products add technology value to that services model. [5] [16]
The opportunity grows as AI moves into everyday production: voice agents, business automation and continuous inference require reliable response times and efficient use of costly GPUs. Buying the equipment is only the start. Customers need the whole system working together, often under demanding uptime commitments. That creates an opening for an experienced builder and operator. [8] [14]
The Earnings Breakout Is the Main Event
October’s results beat FactSet expectations by approximately 30% on adjusted EPS and 9% on revenue. The new fiscal 2027 midpoints also exceeded the cited analyst models: $3.39 EPS and $2.21 billion sales. The significance is the higher earnings trajectory investors now have to evaluate. [3]
Two growth engines are coming into focus. Memory supplies the immediate scale; the AI factory platform creates the possibility of more durable customer relationships. The investment case becomes stronger if deployment wins produce continuing software and operating-service income, with enough gross profit to fund growth and generate cash.
What Makes Penguin Different
| Capability | What it does | Why it matters |
|---|---|---|
| Integrated architecture | Combines partner compute systems with memory, reference designs, software and deployment expertise. [8] | A coordinated system can reach production faster and reduce costly implementation mistakes. |
| ClusterWareAI software | Automates deployment, monitors infrastructure and helps diagnose and remediate GPU problems. [10] [16] | Penguin can sell ongoing operational value after the initial equipment delivery. |
| MemoryAI and advanced memory | Engineers memory solutions; its CXL-based KV cache appliance expands available memory for inference. [13] | Long context windows and concurrent AI users make memory capacity and access a performance constraint. |
| Lifecycle services | Designs, deploys and manages customer infrastructure. [11] [14] | Repeated operating responsibilities can deepen relationships and support expansion. |
The economic distinction: Penguin can participate in AI expansion through equipment, memory and operating expertise while customers finance and own their AI capacity. This differs from a neocloud building a fleet to rent GPU time. It still requires working capital, and competitors can combine systems and services too. The potential advantage is Penguin’s integration of memory engineering, cluster software and operating experience; superior returns must show up in customer performance, margins and cash generation.
The Growth Driver Investors Should Understand
Memory contributed approximately 91% of Q4’s total year-over-year revenue increase, calculated from the segment results. Advanced Computing grew much more slowly at the segment level, although management reported substantially faster growth in its non-hyperscale AI infrastructure business. The recent quarter demonstrates a memory surge; the outlook asks investors to believe the next phase also brings stronger AI infrastructure growth. [1] [2]
Valuation reference: The $75 current price reference implies about 16.9 times management’s fiscal 2027 adjusted EPS midpoint and about 21.4 times its GAAP EPS midpoint. These are calculations using guidance, rather than realized earnings or a price target. They show why delivering the outlook matters so much to the share-price debate. [1]
02CEO Playbook — Own the Architecture and the Operations
Kash Shaikh became CEO on February 2, 2026. His background includes leading Securonix and Virtana, alongside enterprise infrastructure roles at Dell and HPE. His playbook connects two existing strengths—memory and complex computing systems—to a broader AI factory platform. [5] [6]
The Destination · Production AI at Scale
“As enterprises move from proofs of concept to production AI environments, Penguin’s focus on performance, reliability and time-to-value is increasingly critical.”
— Kash Shaikh · CEO appointment announcement · February 2, 2026 · Source
What it means: The target is the customer ready to run AI as an operating business. Reliability, deployment speed and predictable economics become purchasing criteria. Penguin wants to make those outcomes its product.
The Architecture Shift · Memory Becomes Central
“We believe this is driving a re-architecture of the data center across compute, memory, interconnect, and software.”
— Kash Shaikh · Q2 earnings call · April 1, 2026 · Source
What it means: More inference demand creates an opportunity across the system. Penguin’s thesis is that memory and infrastructure should be designed together. CXL connects additional memory to a system; a KV cache retains intermediate information used while generating AI responses, reducing repeated work.
“As inference and agentic AI workloads become more persistent and context-rich, memory is increasingly becoming one of the primary performance and scalability bottlenecks.”
— Kash Shaikh · Q3 earnings announcement · July 7, 2026 · Source
Why it matters: Solving a customer’s performance constraint can support differentiated engineering value. The degree of pricing power remains an open question when part of the revenue increase comes from higher component prices.
The Operating Layer · Keep the Factory Productive
“This release advances our vision of intelligent, self-managing AI infrastructure through AI-driven operations, automated remediation, and deep infrastructure awareness.”
— Ian Colle · Chief Product Officer at announcement · June 25, 2026 · Source
What it means: Automated fault detection and recovery can protect the productivity of an expensive GPU fleet. This is the software argument behind Penguin’s platform: customers should keep paying for operational results after the hardware is installed.
“This designation validates Penguin’s deep capabilities to design, build, deploy, and operate full-stack AI factories at scale.”
— Kash Shaikh · NVIDIA partner announcement · June 23, 2026 · Source
What it means: NVIDIA’s specialized partner designation adds credibility to the delivery capability. It does not confer exclusivity or guarantee contracts. Deepgram’s deployment with Dell provides a concrete customer example of Penguin coordinating the surrounding infrastructure.
The Commercial Model · Become the Lifecycle Partner
“This allows us to serve as the single builder and operator of AI factories across the entire lifecycle for our customers.”
— Kash Shaikh · Q4 earnings call · October 6, 2026 · Source
The upside mechanism: An initial system deployment can lead to software adoption, managed operations and later expansion. Investors need evidence that these continuing responsibilities generate attractive profit and collections, rather than mainly adding equipment volume.
The Capital Plan · Fund a Bigger Business
“Demand for memory and AI infrastructure is accelerating as inference and agentic AI workloads move into production at scale.”
— Kash Shaikh · financing announcement · July 17, 2026 · Source
What it means: The convertible financing gives Penguin more flexibility to support demand. A zero coupon reduces regular cash interest, but principal must still be repaid or converted, and growth ties up cash before customers pay.
The Inflection · Both Businesses Must Deliver
“As we enter fiscal 2027, our memory business remains strong, and our AI Infrastructure business is accelerating further.”
— Kash Shaikh · Q4 earnings announcement · October 6, 2026 · Source
What it means: The next test is broader growth. Memory has already supplied the earnings acceleration; AI factory deliveries must now validate the expanded platform strategy.
“We enter fiscal 2027 with strong AI-driven momentum, meaningful operating leverage, and a clear strategy to scale our AI Factory Platform business”
— Kash Shaikh · CFO appointment announcement · October 6, 2026 · Source
The management priority: Scale gross profit faster than overhead, then convert the resulting earnings into cash. New CFO Stephen Cumming joins at a point when financial discipline matters as much as winning the next deployment.
Financial Transformation — From Memory Surge to Platform Scale
USD millions unless stated. Adjusted means non-GAAP; guidance is a forecast. Source: company financial tables. [1]
| Metric | Q4 FY2025 | Q4 FY2026 | Change / interpretation |
|---|---|---|---|
| Revenue | $337.9 | $566.7 | +67.7% |
| Integrated Memory revenue | $132.2 | $340.8 | +157.9%; 60% of latest quarterly sales |
| Advanced Computing revenue | $138.3 | $154.0 | +11.4% |
| Optimized LED revenue | $67.4 | $71.9 | +6.6% |
| GAAP operating income | $12.4 | $69.5 | Operating improvement independent of the tax benefit |
| Adjusted operating income | $39.2 | $89.8 | +129.3% |
| Adjusted operating margin | 11.6% | 15.8% | +4.2 percentage points |
| Adjusted gross margin | 30.9% | 28.8% | Growth came with a lower YoY margin rate |
| GAAP diluted EPS | $0.11 | $1.29 | Includes substantial tax and other adjustments |
| Adjusted diluted EPS | $0.43 | $1.00 | +132.6% |
| Full-year measure | FY2025 actual | FY2026 actual | FY2027 management outlook |
|---|---|---|---|
| Revenue | $1,368.8 | $1,731.5 | Approximately $2,430 midpoint; growth 30%–50% |
| Adjusted EPS | $1.90 | $2.87 | $4.45 ± $0.70 |
| GAAP EPS | $0.28 | $2.60 | $3.50 ± $0.70 |
| Operating cash flow, continuing operations | +$113.2 | −$151.9 | No quantitative cash-flow target in release |
| Capital expenditures / equipment deposits | $9.0 | $11.6 | Monitor alongside working capital |
Earnings quality: Q4 included a $57.6 million GAAP income-tax benefit and a $33.2 million debt-conversion inducement expense. Adjusted earnings remove these and other items. The continuing-operations cash-flow comparison is used consistently above; total FY2025 operating cash flow was $109.1 million after discontinued operations. Memory’s contribution to incremental revenue and valuation multiples are Arena calculations from reported figures. [1]
03CEO Signals Timeline — The Recent Strategic Shift
| Date | Signal | Strategic interpretation |
|---|---|---|
| February 2, 2026 | Shaikh takes over as CEO. [6] | A leader with software and enterprise infrastructure experience assumes responsibility for the platform transition. |
| March 16–17, 2026 | MemoryAI launch and Deepgram deployment. [13] [14] | The strategy takes product and customer form: memory expansion plus real-time production inference. |
| April 1, 2026 | First earnings call under Shaikh; higher FY2026 outlook. [7] [8] | Management describes a wider opportunity across enterprise, sovereign AI and neocloud customers. |
| June 23–25, 2026 | NVIDIA specialization and ClusterWareAI expansion. [10] [11] | Delivery credentials and operational software advance together. |
| July 7–17, 2026 | Q3 acceleration, higher outlook and financing. [9] [12] | Demand becomes financial growth; capital supports its next phase. |
| October 6, 2026 | Record Q4, higher FY2027 outlook and large neocloud engagements. [1] | The commercial story expands from isolated installations toward substantial operating responsibilities. |
The progression: The recent sequence connects a leadership change, a defined product architecture, deployed customer applications and accelerating results. The remaining gap is evidence of sustained cash generation from that strategy.
04News Flow — The Material Developments
Ten material developments from the past nine months, newest first. Dates are announcement/publication dates. Star weights reflect editorial strategic importance, rather than expected stock returns.
| Date | Headline & What It Signals | Type | Weight |
|---|---|---|---|
| October 6, 2026 | Record Q4 and higher FY2027 outlook Announced: Record earnings; new neocloud engagements, including the 36,000-GPU Norway deployment and operations assignment. What it means: The biggest recent update combines current profit growth with a larger commercial opportunity. The $3 billion and $10 billion contract figures discussed in the release belong to customers’ downstream contracts, not Penguin revenue or bookings. [1] |
Earnings / Contracts | ★★★★★ |
| July 17, 2026 | $750 million financing closes at a zero coupon Announced: 0% convertible senior notes due 2031; concurrent refinancing and capped calls. What it means: Improves funding flexibility and maturity profile. Capped calls are intended to mitigate dilution up to an initial $175.05 cap, subject to their terms; zero interest does not eliminate debt or all dilution. [12] |
Financing | ★★★★☆ |
| July 7, 2026 | Q3 revenue jumps 48%; outlook rises Announced: Revenue $478.7 million, adjusted EPS $0.84; fiscal 2026 adjusted EPS outlook raised to $2.60 ± $0.05. What it means: The growth acceleration was already visible before Q4, strengthening the case that October’s result has a broader demand backdrop. [9] |
Earnings | ★★★★★ |
| June 25, 2026 | ClusterWareAI adds AI-powered operations Announced: New operations agent, GPU remediation for Kubernetes workloads and expanded health visibility. What it means: Strengthens the continuing software proposition: improve uptime and help operators resolve faults across a factory. [10] |
Product / Software | ★★★★☆ |
| June 23, 2026 | NVIDIA AI Factory specialization Announced: Penguin joins NVIDIA’s invitation-only group of specialized solution providers. What it means: Validates relevant competencies and operating experience; helps customer credibility without establishing exclusivity. [11] |
Strategic Partnership | ★★★☆☆ |
| April 1, 2026 | Q2 outlook rises despite lower quarterly revenue Announced: Revenue $343 million, down 6%; full-year growth midpoint raised to 12%, adjusted EPS midpoint to $2.15. What it means: Memory demand supports the outlook while large infrastructure deployments remain uneven. This is the starting point for the later acceleration. [7] |
Earnings | ★★★★☆ |
| April 1, 2026 | Brazil memory divestment completes Announced: Remaining 19% stake sold for $46.08 million; the transaction closed March 30. What it means: Releases capital from the Brazilian commodity module business and completes that exit. Publication date and transaction date are distinguished. [15] |
Portfolio / Capital | ★★★☆☆ |
| March 17, 2026 | Deepgram selects Penguin for enterprise voice AI Announced: Production inference infrastructure delivered with Dell and NVIDIA technology. What it means: A named customer deployment illustrates the platform’s practical value in latency-sensitive voice applications. Contract value was not disclosed. [14] |
Customer / Partnership | ★★★★☆ |
| March 16, 2026 | MemoryAI KV cache server launches Announced: CXL-based memory appliance supporting up to 11 TB, compatible with NVIDIA Dynamo. What it means: Creates a product designed to address inference memory constraints. Future sales and economics determine its investment significance. [13] |
Product / Memory | ★★★★☆ |
| February 2, 2026 | Kash Shaikh becomes CEO Announced: Mark Adams retires; Shaikh assumes the CEO and board roles. What it means: A material leadership change precedes the AI factory strategy and subsequent growth acceleration; results will test execution. [6] |
Leadership / Strategy | ★★★★☆ |
Inside the October Update — The Important Commercial Wins
Beyond Norway, Penguin disclosed a GB300 NVL72 platform assignment for a neocloud backed by a South Korean technology company; deployment and 24/7 operations for a publicly traded neocloud; and a Lektra engagement covering distributed AI micro data centers using existing carbon-free energy. The update also identified additional AI infrastructure and memory supply arrangements. Most counterparties and Penguin contract values were not disclosed. [1]
Management reported 99% Q4 growth in non-hyperscale AI infrastructure, which accounted for 66% of Advanced Computing revenue. That faster-growing business sits within a segment still affected by declining legacy activity. Total services sales nevertheless fell 11% to approximately $57 million. Investors should distinguish new multi-year operating wins from the overall reported services trajectory. [2]
News Flow Analysis
The most useful connection is product → customer → financial performance. MemoryAI addresses a bottleneck, Deepgram demonstrates deployment capability, and ClusterWareAI adds operational functionality. Those developments give the factory-platform strategy substance beyond its branding.
The latest earnings change the financial stakes. Investors now have a higher profit forecast to test against actual deployments. A software-and-services attachment can improve the quality of equipment relationships, but a large project announcement alone cannot establish recurring revenue, margin or cash value.
Upcoming Catalysts
- Fiscal 2027 deliveries: Evidence that recently won projects move into revenue on schedule.
- Memory economics: Whether demand and pricing remain supportive, and how procurement costs affect gross profit.
- Software and managed services: More disclosure of recurring revenue, attach rates and renewal behavior.
- Cash conversion: Collections and inventory turns catching up with reported growth.
- Next quarterly results: Validation of the annual outlook; the next reporting date was not confirmed in the reviewed releases.
05Bull / Bear Debate — Growth Quality Is the Test
The Bull Case
Demand broadens across the system. Inference needs compute, memory and reliable operations, giving Penguin multiple routes to participate.
Integrated delivery can earn customer trust. Memory technology, cluster software and implementation experience may make Penguin harder to replace within complex deployments.
Operating leverage can magnify growth. If gross profit rises faster than overhead, a larger business can produce disproportionately higher earnings.
More customers can support expansion. The 17 new AI infrastructure customers and 12 expanding customers reported for fiscal 2026 provide a base for follow-on business. [1]
The Bear Case
The memory cycle can reverse. Higher prices help sales today but can unwind; procurement costs and demand need separate scrutiny.
Cash is already a constraint. Inventory and receivables absorb funding as customers ramp. Accounting profits must translate into collections.
Hardware can dilute margin quality. Larger equipment deliveries may raise revenue faster than gross profit; continued services economics need proof.
Customers and partners carry risk. Large project timing, neocloud funding, component supply and competition can change the earnings path.
The Evidence That Resolves the Debate
Track gross-profit growth and operating cash flow alongside revenue. Watch the deployment cadence and recurring software-and-services contribution. These measures distinguish a sustainably valuable platform from a temporary volume-and-pricing surge.
Balance-sheet context: Fiscal year-end cash was approximately $647 million, inventory $749 million and receivables $796 million. Current plus long-term debt carrying amounts totaled approximately $789 million. The company also reported convertible preferred equity separately. Low physical capital expenditure therefore coexists with substantial funding needs. [1]
06Questions for Management — What Investors Need Next
- How much of memory growth comes from units, pricing and customer gains? Provide a bridge investors can use when the pricing cycle changes.
- What are Penguin’s own economics on the Norway engagement? Disclose revenue timing, software and service scope, expected profitability and payment protections, rather than the customer’s downstream contract value.
- How much contracted recurring revenue does the platform generate? Separate software, managed operations and initial deployment services.
- What portion of inventory is covered by firm customer commitments? Explain deposits, cancellation rights, obsolescence exposure and supplier terms.
- When should operating cash flow turn positive? Identify the expected collections and inventory milestones behind that improvement.
- What can interrupt fiscal 2027 delivery? Quantify exposure to GPU availability, memory supply and customer project delays.
- Where is the measurable competitive advantage? Show deployment time, utilization, reliability and cost per AI output against alternative designs.
- How does financing affect earnings per share? Explain the assumed dilution, capped-call treatment and preferred-share claims across stock-price scenarios.
07Arena Signals Takeaway — The Next Test Is Cash and Execution
The latest report gives the story financial momentum and a larger customer opportunity. The next stage needs to demonstrate that those relationships produce sustained gross profit, repeat business and cash. That is the evidence most likely to determine the platform’s long-term value.
What to watch: deployment execution, memory pricing versus costs, continuing software-and-service income, and cash conversion. Revenue growth alone will not answer those questions.
Sources & Research Notes
- Fourth-quarter and full-year fiscal 2026 earnings announcement · October 6, 2026
- Fourth-quarter fiscal 2026 earnings call · October 6, 2026 · transcript
- Investor’s Business Daily · earnings and FactSet expectations · October 6, 2026
- Barron’s · memory growth, cash flow and stock reaction · October 7, 2026
- Company leadership · CEO biography and official portrait
- CEO transition announcement · February 2, 2026
- Second-quarter fiscal 2026 earnings announcement · April 1, 2026
- Second-quarter earnings call · company-published remarks and Q&A · April 1, 2026
- Third-quarter fiscal 2026 earnings announcement · July 7, 2026
- ClusterWareAI operations and automated remediation announcement · June 25, 2026
- NVIDIA AI Factory Specialized Partner announcement · June 23, 2026
- Convertible financing closing announcement · July 17, 2026
- MemoryAI CXL-based KV cache server announcement · March 16, 2026
- Deepgram and Dell inference deployment announcement · March 17, 2026
- Brazil memory business divestment announcement · April 1, 2026
- ClusterWareAI · official product description
- CFO appointment announcement · October 6, 2026
- Chief product officer appointment · March 2, 2026
Primary company materials anchor the strategy, products and financial figures. Independent reporting supplies consensus comparisons and market context. Quotations are short verbatim excerpts; interpretation and star weights are editorial analysis. Numbers are rounded; forecasts are distinguished from actual results. Research cutoff: October 7, 2026. Share-price calculations use the $75 price reference for October 7, 2026.